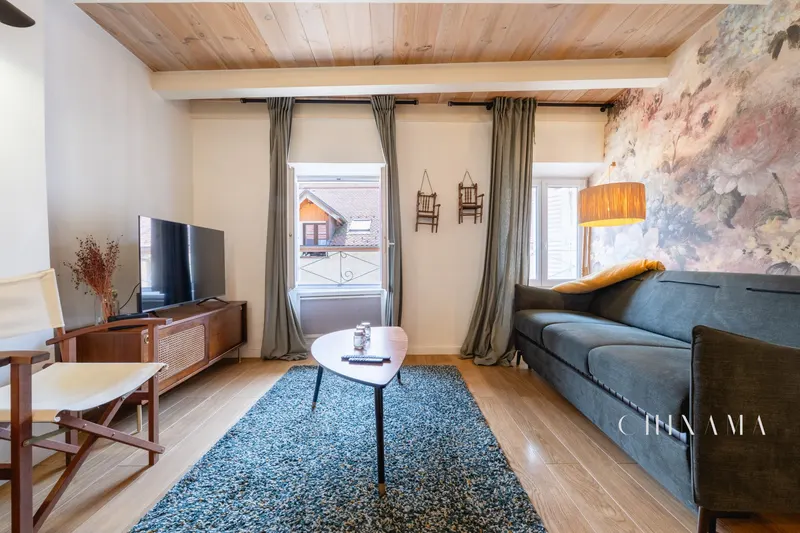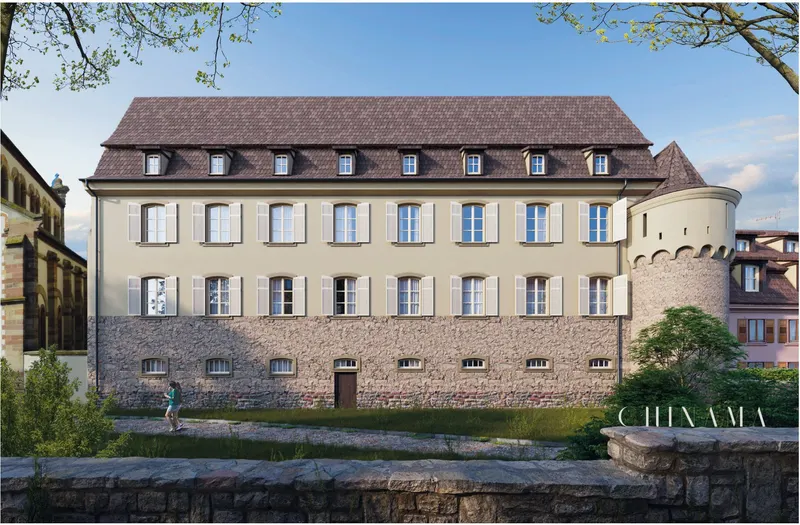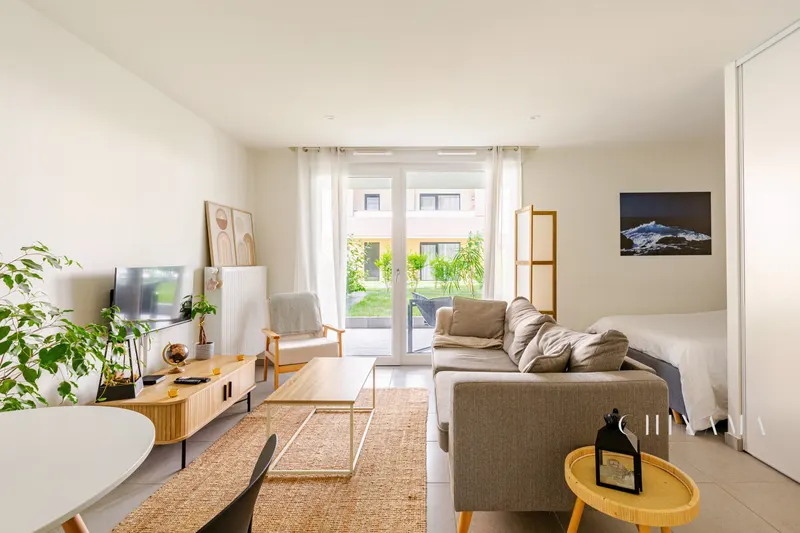
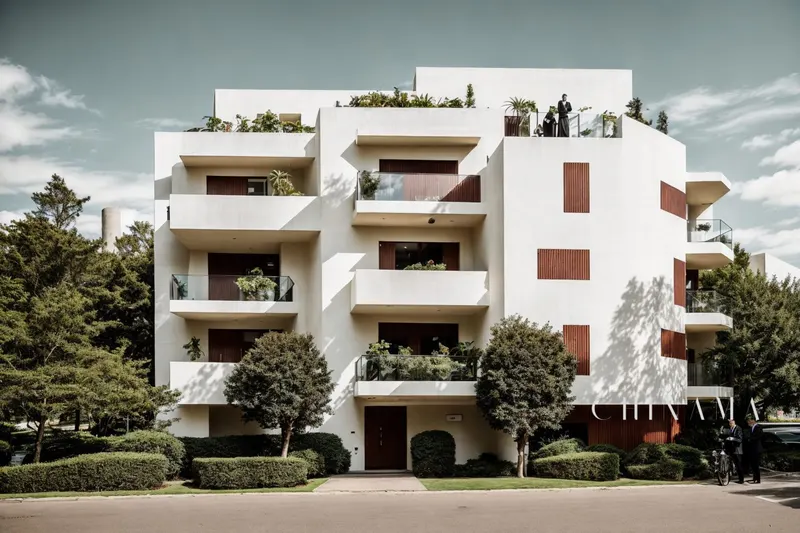
The property
On the third floor of a four-storey building, the apartment offers 67 m² of living space and 71 m² of floor area. The 27 m² living room opens onto a west-facing 10 m² balcony.
Two bedrooms, a bathroom and a separate WC complete the apartment, sold unfurnished.
A bus stop, crèche, shops, restaurants and doctors are less than five minutes' walk away; nursery and primary schools about ten minutes. The apartment is eligible for fibre broadband.
- 10 m² balcony
- West facing
- Shops within walking distance
- Fibre broadband
Key features
| Type | Apartment, 3 rooms |
| Living space | 66.98 m² |
| Floor area | 71 m² |
| Living room | 27 m² |
| Bedrooms | 2 |
| WC | 1 |
| Floor | 3 |
| Floors in the building | 4 |
| Aspect | West |
| Balcony | 10 m² |
| Furnishing | Unfurnished |
| Reference | VA1924 |
Price and legal information
Price: €520,000. Agency fees are paid by the seller. Part of a co-ownership of 15 lots. No proceedings in progress. Not subject to an energy performance certificate. Information on the risks to which this property is exposed is available at georisques.gouv.fr.
Mentions légales de l'annonce : Honoraires à la charge du vendeur. Dans une copropriété de 15 lots. Aucune procédure n'est en cours. Non soumis au DPE. Les informations sur les risques auxquels ce bien est exposé sont disponibles sur le site Géorisques : georisques.gouv.fr.
Your financing
Estimate the monthly repayment for this property in a few seconds. Change the deposit, term or rate: the figures update instantly.
| Property price | €520,000 |
| Estimated notary fees | €41,600 |
| Amount to borrow | €519,600 |
| Estimated monthly repayment, excluding insurance | €2,963 |
| Recommended minimum net monthly income | €8,466 |
| Total interest cost | €191,517 |
Indicative simulation, excluding borrower insurance and guarantee fees, based on the assumptions above. It is neither a loan offer nor a credit proposal: Maison Chinama is not a credit intermediary. The default rate is the average French mortgage rate for August 2026 published by the Observatoire Crédit Logement/CSA; your rate will depend on your profile and your bank. Notary fees are an estimate; the exact amount is calculated by the notary. The recommended income is based on a 35% debt-to-income ratio, the ceiling set by the French High Council for Financial Stability including insurance, so it is a minimum. A loan is a commitment and must be repaid: check your ability to repay before committing.
Interested in this property?
Mathias will answer your questions and arrange a viewing.